The position
A claim you will have to defend
Marketing claims get retired quietly. Financial positions get audited. Treat carbon as the second and the first takes care of itself.
Science-led carbon & climate intelligence
We do the hard part — finding and screening carbon that genuinely delivers — so your goals rest on credits that hold.
Scroll — the integrity story, in six chapters
The market has divided
The voluntary carbon market has split in two. One half is cheap, abundant, and increasingly a liability. The other is scarce, scrutinised, and defensible.
We operate only in the half that lasts, and we develop supply at its source so our clients are not left competing for it.
Cheap, abundant, increasingly a liability.
Scarce, scrutinised, defensible.
The price gap proves it: in 2025, high-rated credits (A–AAA) averaged about $14.80/tonne while low-rated credits (CCC–B) averaged about $3.50 (MSCI Carbon Markets, 2025). Credits meeting the ICVCM Core Carbon Principles command a premium reported at up to 400% (Fiegenbaum Solutions, 2026), and top-tier credits traded roughly 50% higher than the lowest end over the year (Calyx Global & ClearBlue Markets, 2026).
What the market is paying — third-party data, not ours
What a serious buyer needs
A Fortune 500 climate claim is now a financial and legal position, not a line of marketing. It must be additional, permanent, independently verified, free of double counting, and demonstrably good for the people and ecosystems it touches. That is the whole of our work, and the whole of The Five Checks.
This is now the norm at the top of the market: 51% of Fortune Global 500 companies hold net-zero targets (Terrapass / SBTi, 2026), and buyers are visibly selective — credits rated A or higher made up 36% of 2025’s retirement value, even as 43% of 2024 retirements still came from low-rated projects (MSCI Carbon Markets, 2025).
The position
Marketing claims get retired quietly. Financial positions get audited. Treat carbon as the second and the first takes care of itself.
The exposure
43% of 2024 retirements still came from low-rated projects. Price is the reason; exposure is the cost.
The correction
Credits rated A or higher made up 36% of 2025’s retirement value. The market is repricing integrity in real time.
Why buyers choose us
We source carbon directly from the projects that create it — no middlemen, no reselling on a spread.
Nothing reaches you until it passes The Five Checks. If we wouldn’t hold it, we won’t supply it.
Our projects do genuine good on the ground — for communities and ecosystems — not just on paper.
You see exactly what you’re buying, where it comes from, and how it’s retired.
How we ensure quality — The Five Checks
All 5 checks must pass before we supply a credit.
It wouldn’t have happened without carbon finance.
The impact lasts, protected against reversal.
Conservative numbers, independently verified.
No double counting, transparently retired.
Real community and environmental benefit.
Fail one, and we don’t supply it.
What we do
We find, screen and supply high-quality carbon — to order, as a managed portfolio, or from our own projects.
Explore
I-RECs to cut your Scope 2 — verified, correctly matched, defensible.
Explore
The measurement, reporting and target-setting that make your claims defensible.
Explore
Our Model
When our projects create value, that value is shared with the people and communities who make them possible.
Impact — proven, not promised
Take one agroforestry programme we’ve developed with farming communities across Gujarat and Rajasthan:
An afforestation–reforestation project — pomegranate, guava, mahogany and custard apple — third-party verified, with on-site and satellite MRV, and additionality proven.
SDGs advanced
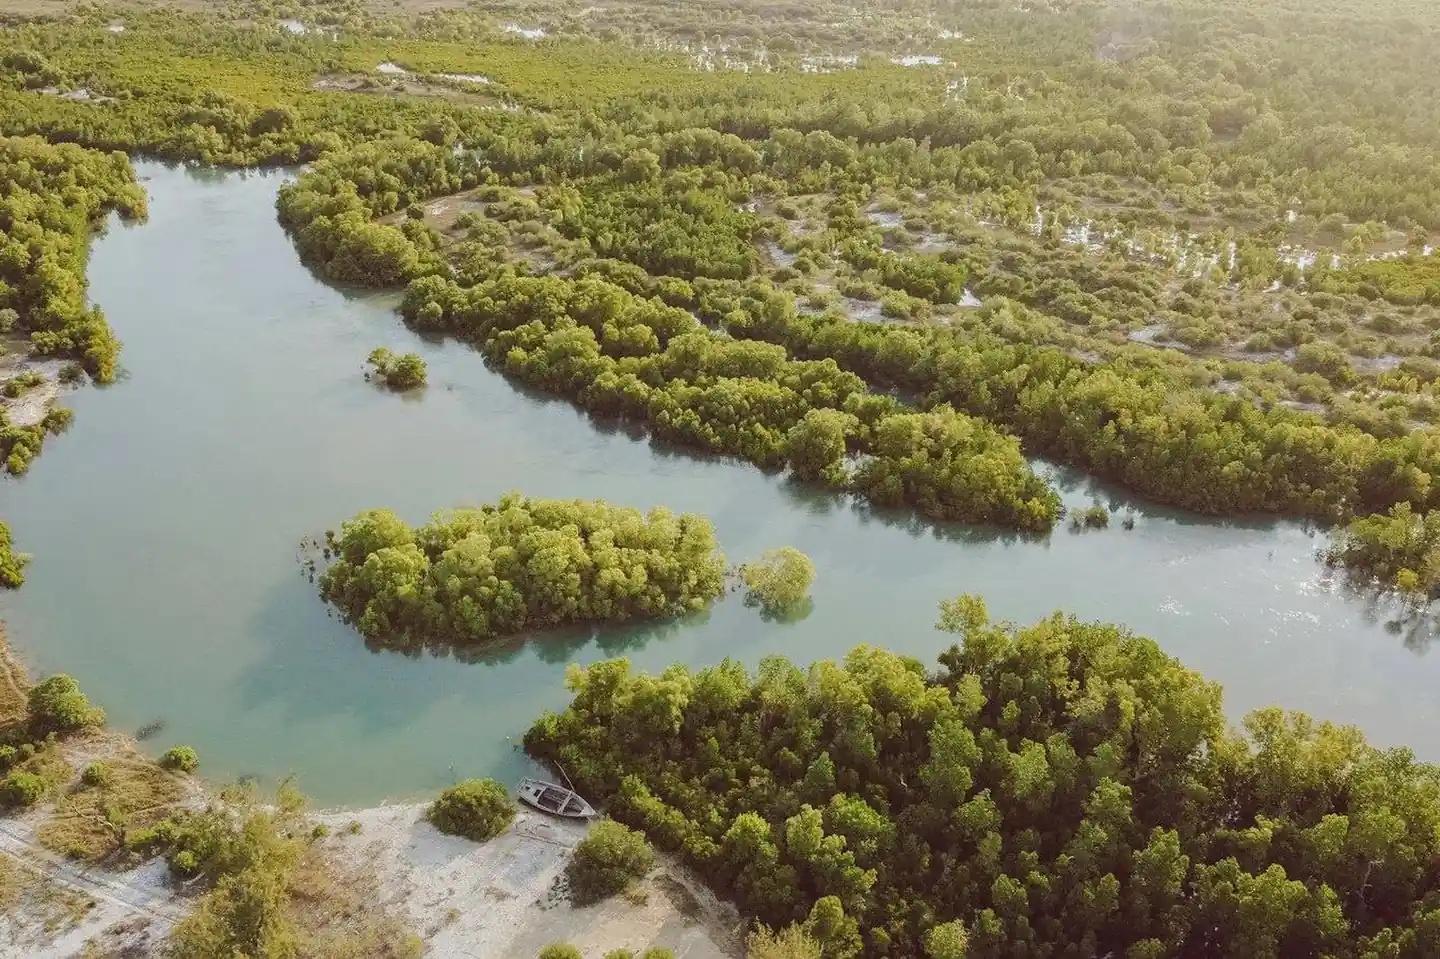
This is exactly the profile the market now rewards: high-quality afforestation/reforestation (ARR) spot prices rose to around $24/tonne by September 2025, up sharply over the year (green.earth, 2025), and nature-based projects dominate the premium-priced segment alongside engineered removals (Grand View Research, 2026).
Securing supply, developing a project, or mapping a net-zero pathway: senior specialists, start to finish. A reply within one business day.